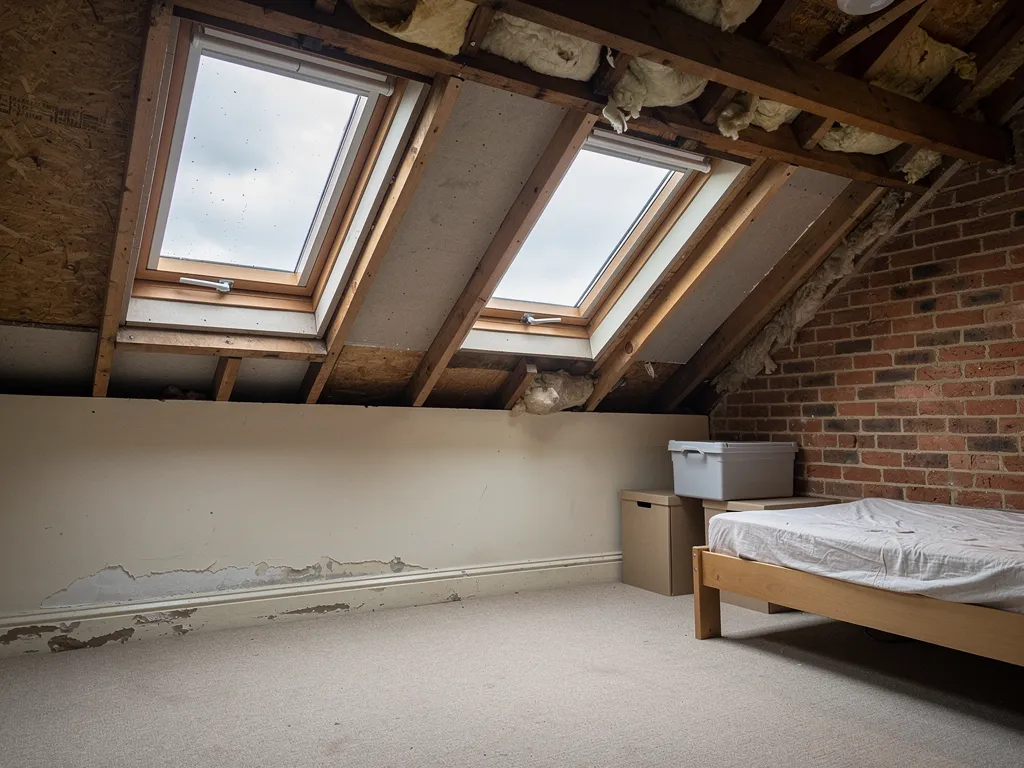
Equity release lets homeowners, usually in later life, draw out money tied up in a house without moving out. The provider lends against the value of the property, so the property has to meet the provider's idea of acceptable security. Spray foam in the roof has become one of the things that can unsettle that judgement.
If you are reading this, you may already have been told something. Perhaps an adviser mentioned foam during an enquiry, a valuer flagged the loft, or a provider asked for a survey you did not expect. Perhaps you simply sprayed the roof a few years ago to cut the heating bill, and now wonder whether it will matter when you want to release funds.
The answer depends on the provider, the product and the state of your roof, and policies change. So this guide does not predict any outcome. It sets out what the RICS advises, what was reported about named firms and lenders in November 2024, what you can ask before you commit, and how roof work, including foam removal, can sit alongside an application. We are roofers, not financial advisers, so we only speak to the roof side of it.
Why a provider cares what is under the tiles
An equity release provider takes the house as security. Whatever it lends, it expects to recover from the sale of the property, perhaps many years from now. That makes the provider cautious about anything that could shrink the sale value or complicate a sale. Spray foam in a roof is such a thing, because of the way it hides the timbers and the way some buyers' lenders treat it.
The RICS consumer guide of March 2023 spells out the connection. It lists foam among the things that may sway the professional opinion a surveyor forms about what the house is worth. A valuation, not a roofer, sets the amount a provider will offer, so anything that colours the valuer's opinion can change the offer, delay the case or end it.
The same guide also urges anyone considering foam to ask their lender if its lending rules allow it. That advice was written for people thinking of installing foam, but the logic carries over. A lender with a rule about foam has a rule about foam whether the product went in last month or a decade ago.
What a valuer sees and what they can't
A valuer visiting your home usually has a short time and looks mainly at condition and comparable sales. They can see a foam-lined loft from the hatch, and they may note it. What they cannot see is the state of the rafters behind it. That uncertainty is exactly what the RICS guidance worries about, and it can lead to a retention, a request for a specialist report or a decline. Our guide to whether spray foam damages roof timbers explains what that report looks for and why the answer is rarely simple.
What was reported in November 2024
Today's Conveyancer, on 20 November 2024, reported on a national broadcaster's investigation into how lenders treat homes with spray foam. By that date, several named lenders had said they would decline mortgages on foamed homes, while others were considering applications one at a time. The report named specific mortgage lenders in each group, and it also named More 2 Life, an equity release provider, among the firms covered.
Individual lender positions from November 2024 are dated, so check the current policy before relying on any of them. Policies shift as the market learns more, as valuers gather experience and as the RICS and the industry revise their guidance. A provider that refused cases then may take them now, with conditions, and one that accepted them may have tightened up.
What to do with a dated report
Treat it as evidence of the direction of travel and as a prompt to ask. Phone or write to the provider, or ask your adviser to do so, and put the question in terms of your own house: foam in the roof, installed on a particular date, with or without paperwork. Ask for the answer in writing, and note the date, because it will be out of date at some point too.
Do not hide foam from a valuer or from a provider. Concealing it tends to make a bad outcome worse, because the survey will turn it up and the application will then fail on trust as well as on the roof.
Whatever you hear, please don't treat a lender's refusal as proof your roof is damaged. A policy is a business decision about risk. Your roof may be perfectly sound and still fall outside a lender's rule.
Questions to put to an adviser before applying
Before any application, a short list of questions saves weeks. Start with the provider's current written policy on spray foam in a roof. Does it lend at all, and under what conditions? Will it accept foam if the roof has been inspected? Does it want removal evidence, or a specialist report on the timbers, or both?
Next, ask who pays for what. If the provider asks for a report, find out whether it names the surveyor or lets you choose, and what qualifications it expects. A report that the provider does not accept is money wasted, so confirm the format in advance. Ask how long a report stays valid, because a case that runs on can outlast it.
Then ask about the offer itself. If the valuer applies a retention, meaning the provider holds back part of the sum until a problem is fixed, how much could that be, and what evidence releases it? Ask whether works carried out after the offer can be inspected and signed off without a fresh valuation.
What to gather for them
Pull together what you hold on the foam. That means the installer's name and the date, any invoice or product details, any guarantee, and any survey that mentions it. Doing the removal yourself leaves you without the paper trail a provider wants, which is one reason people avoid it.
If the installer has gone out of business, say so. A provider reading an application wants to know that the person who sprayed the roof cannot be asked to put anything right. You are not the first homeowner in that position, and honest disclosure helps more than a gap in the paperwork.
Finally, take independent advice from a qualified equity release adviser. Spray foam is one issue among many in a decision that affects your estate and your family.
Where roof work can fit into an application
Roof work can help an application, but only if it is done for a reason the provider recognises. There are broadly three situations. In the first, the roof is sound and the foam is accepted as it stands, and no work is needed. In the second, the provider wants proof about the timbers behind the foam, and a survey with a trial opening supplies it. In the third, the provider will not proceed with foam in place, and the foam has to come out.
For the survey route, a roofer records what is under the foam and where the moisture readings fall. We take photographs of your own roof, of the rafter ends, the timber on the wall top and the underlay at the opened sections, and we write up what we find alongside the quote. Whether a provider accepts a roofer's report in place of a chartered surveyor's is the provider's decision, so ask in advance.
Removal as a way through
Removal is not a first resort, but it can be the right one when the provider has said no. MyBuilder (updated 21/08/2026) gives a typical UK range of £20 to £50 per square metre for removal, with an average around £1,500, plus £100 to £200 for assessment and £150 to £400 for disposal. Foam stuck hard to the underside of tiles can raise the labour, so the quote reflects the actual roof once surveyed.
The RICS warns that taking foam off might harm the structure behind it, which is one reason it is a job for people who strip foam regularly and who check the wood as it comes into view. If you decide to go that way, read our spray foam removal service to see how the work runs from survey to clean loft.
The order to do things in
Sequence matters, because spending on the roof before talking to a provider can waste money, and signing for a loan before sorting the roof can leave you stuck. A sensible order starts with questions. Ask the provider, through an adviser, whether foam is acceptable. Get the answer in writing.
If the answer is yes, with conditions, find out what the conditions are and whether a survey would meet them. Book the survey, keep the report and send it to the provider before the valuation, not after. If the answer is no, then the choice is between a different provider, a different way of raising money, or removal. Removal makes sense when you want to stay in the house, the foam is the only obstacle and the roof has been checked.
If you do remove it, ask for a written record. You want a before-and-after account of what was found, photographs of the opened timbers, a note of any repairs and details of what insulation went back. That evidence is what a later valuer or buyer's surveyor will ask to see.
A word about the replacement
The loft will need insulating again after removal, and the provider may want to know what was used. We set out the options in our guide to insulating the loft after spray foam removal. A breathable approach with proper ventilation is easier to explain to a valuer than another sealed layer, and it leaves the timbers open to inspection.
Finally, allow time. Roof work, a report and a revised valuation can add weeks to a case, and a provider's offer can lapse while you wait. Tell your adviser what you are doing so the application can be paced around the work.
When the roof and the sale go together
Equity release is not always the end of the story. Some homeowners release funds and later sell, or their estate sells, and then the next buyer's lender takes its own view of the foam. What you do now with the roof therefore affects an eventual sale as much as the application today.
If the foam stays, you leave a future seller or executor with a question and little paperwork. If it goes, with records, they inherit a clean answer. That is a reason to keep every document and photograph from any roof work, and to store them with the deeds or give a copy to a family member or solicitor.
The detail of what buyers, surveyors and lenders ask at sale is covered in selling a house with spray foam insulation, and it is worth reading even if a sale is a long way off.
Listed and protected homes
The RICS guide adds that foam should not go into a listed or otherwise protected building without consent being given first. If your home is listed and was sprayed without consent, mention that to your adviser early and speak to the conservation team at the council, or the South Downs National Park Authority where the house lies within the Park. The position of the provider and the position of the planning authority are separate matters, and both need to be understood before work starts.
As always, the survey comes first. We look at the roof, explain what is there, and send you a written quote with one overall price. Use it as you see fit, whether that is to satisfy a provider, plan removal or simply know where you stand.